
Vehicle Financing Rating Guide for NZ Buyers
Learn how to rate NZ vehicle finance offers, compare car loan costs, fees and balloon payments, and spot risky deals before you sign.
Vehicle financing is the quality of the finance offer attached to a car, not the quality of the car itself. For New Zealand buyers, it matters because a sharp-looking weekly payment can hide high interest, large fees, or a risky final balloon payment that makes the car far more expensive than it first appears. (consumerprotection.govt.nz)
What Goes Into the Rating
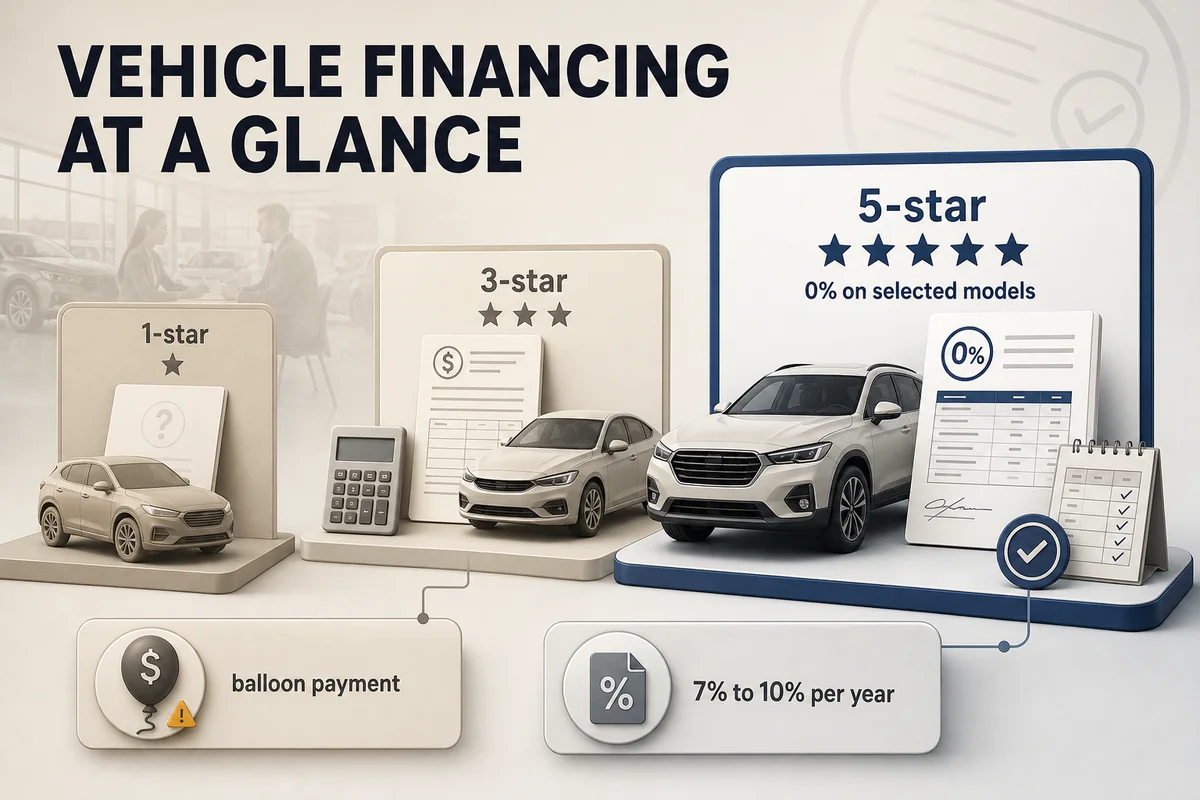
A financing rating usually measures how easy, flexible, and transparent the finance offer is. At the low end, a 1-star result means there is no finance information at all, or finance is not offered. A 2-star result means the seller mentions finance but gives you almost nothing useful beyond “finance available” or “ask us about payments”. That is weak because you cannot compare the real cost without interest rates, fees, term length, deposit requirements, or repayment examples. (consumerprotection.govt.nz)
A 3-star rating is the middle ground. This is where you start seeing proper detail such as an interest rate, a repayment example, a loan term, or whether the finance is hire purchase or a standard secured loan. That is enough to begin comparing deals, but it may still leave out important details like establishment fees, early repayment charges, or what happens at the end of the contract. Under New Zealand’s Credit Contracts and Consumer Finance Act, lenders must disclose key terms including interest, fees, payment details, cancellation rights, and security interests before you sign. (consumerprotection.govt.nz)
A 4-star rating means the offer is both competitive and well explained. You would expect more than one finance structure, such as standard finance alongside a balloon or guaranteed future value style product, clear repayment illustrations, and transparent terms around deposits, fees, and end-of-term options. This is where manufacturer-backed finance can start to look attractive, especially on new cars, because the process is often more polished and the documentation clearer. (moneyhub.co.nz)

A 5-star rating is exceptional. In practice, that usually means very low promotional interest, sometimes even 0% on selected models, strong flexibility around deposit size and term length, online pre-approval tools, and clear end-of-term choices. It should also be easy to see the total borrowing cost, not just the weekly number. A top rating is about transparency as much as price. A flashy deal is not truly 5-star if the lender buries fees or pushes you into an unrealistic final payment. (consumerprotection.govt.nz)
The big features that separate average finance from strong finance are straightforward. First is the interest rate. Recent New Zealand car loan comparisons show mainstream secured car loan rates often starting around 7% to 10% per year for stronger borrowers, while some lenders charge well into the teens or above depending on risk and whether the loan is secured or unsecured. For example, recent published lender reviews show secured rates around 9.40% to 12.15% at one lender and 9.90% to 21.90% at another. (moneyhub.co.nz)

Second is the repayment structure. A standard hire purchase or car loan spreads the cost across fixed repayments. A balloon payment lowers those regular repayments by leaving a lump sum for the end, but that can be risky if you do not have the cash ready or the car has depreciated more than expected. Guaranteed future value products can reduce some of that uncertainty by setting an agreed value at the end, but they usually come with conditions such as kilometre limits and vehicle condition requirements. (moneyhub.co.nz)

Third is fees and contract flexibility. New Zealand lenders must disclose fees, and those fees must be reasonable and related to actual costs. You should check establishment fees, documentation fees, late payment penalties, insurance add-ons, and any early repayment charge. A loan with a slightly higher headline rate can still be the better deal if the fees are lower and you can repay early without a sting. (consumerprotection.govt.nz)
What to Look For
Start with the total cost, not the weekly payment. Dealers know that "$129 a week" sounds manageable, but that number alone tells you very little. Ask for the cash price, deposit, interest rate, loan term in months, all fees, total amount repayable, and any final payment. If they cannot show that clearly, the finance offer should score poorly no matter how attractive the car is. (consumerprotection.govt.nz)

Next, identify the type of finance. If it is a standard loan or hire purchase, ask whether the rate is fixed and whether the car is held as security. If it is a balloon or future value product, ask what the final amount will be on a specific date, what kilometre limit applies, and what happens if the car is worth less than expected. Many buyers focus on getting into the car and do not spend enough time thinking about how they will get out of the contract. (moneyhub.co.nz)
You should also check whether the lender assessed affordability properly. Under the CCCFA, lenders must act responsibly and consider whether the loan is suitable and affordable for you. They must give you a disclosure statement and explain the contract before you sign. You also have a cancellation period of five working days after disclosure for a consumer credit contract, although the exact effect depends on whether you have already taken the vehicle. (consumerprotection.govt.nz)

A good financing rating should reward transparency around extras. Credit insurance, mechanical warranties, and repayment waivers may be offered alongside the loan. Sometimes they are useful, but sometimes they simply inflate the amount borrowed. Take the contract home, read it slowly, and compare it with an outside lender before committing. That is often the difference between a decent 3-star offer and a genuinely strong 4-star or 5-star one. (consumerprotection.govt.nz)
For used cars, be extra careful. Dealer finance can be convenient, but convenience is not the same as value. On an older hatchback, SUV, or ute, a high interest rate can quickly outweigh any small discount on the sticker price. With fuel prices in New Zealand still high in 2026, your monthly budget needs to cover more than the loan. If you are financing a thirsty petrol SUV or a diesel ute, the running costs can make an “affordable” repayment unaffordable in real life. (moneyhub.co.nz)
NZ Context
New Zealand law gives you more protection than many buyers realise, but only if you use it. The CCCFA requires lenders to disclose key borrowing information, act responsibly, and make standard borrowing costs publicly available. If disclosure is missing or defective, lenders can face limits on enforcing interest and fees. That makes transparency a core part of any financing rating in the NZ market. (consumerprotection.govt.nz)
The Consumer Guarantees Act also matters, but in a different way. If you buy from a registered dealer, your rights around the vehicle itself still apply even if you financed it. Finance does not cancel your consumer rights on the car. Those protections generally do not apply in the same way when you buy privately, which is one reason private-sale finance needs extra caution. (consumerprotection.govt.nz)
NZ driving conditions should shape your finance decision as much as the contract terms. A buyer in central Auckland doing short urban trips may not need to stretch into a high-payment AWD SUV on a balloon structure. A family in Canterbury towing a small trailer or boat needs to remember that towing changes the real cost of ownership, and open-road towing speed for light vehicles is capped at 90 km/h in New Zealand. That matters because a vehicle bought for towing often costs more to buy, more to fuel, and more to finance. (nzta.govt.nz)

The smartest way to use a financing rating is simple. Treat 1-star and 2-star offers as warning signs. View 3-star offers as acceptable but incomplete. Expect 4-star offers to be clear, competitive, and flexible. Reserve 5 stars for finance that is genuinely low-cost, well disclosed, and suited to real Kiwi budgets rather than just getting you over the line in the showroom. (consumerprotection.govt.nz)

Sources
- [1]Consumer Protection NZ: Getting a loan for your car
- [2]Consumer Protection NZ: Credit Contracts and Consumer Finance Act
- [3]Consumer Protection NZ: Consumer rights when buying a car
- [4]NZ Transport Agency: Safe loading and towing for light vehicles
- [5]MoneyHub NZ: Best Car Finance NZ 2026
- [6]MoneyHub NZ: How Car Loan Balloon Payments Work
- [7]MoneyHub NZ: AA Money Car Loans Review
- [8]MoneyHub NZ: MTF Finance Review 2026
- [9]MoneyHub NZ: Car Fuel Costs in New Zealand
- [10]MoneyHub NZ: Mazda Finance Review
© 2026 pyfoi. All rights reserved.